
Do You Know How Much Your House Is Really Worth?Want to know something important you probably don’t have a professional check for you nearly as often as you should? Spoiler alert: it’s

Dated: June 10 2023
Views: 108
Today’s mortgage rates are top-of-mind for many homebuyers right now. As a result, if you’re thinking about buying for the first time or selling your current house to move into a home that better fits your needs, you may be asking yourself these two questions:
Here’s context you need to help answer those questions.
The 30-year fixed-rate mortgage is largely influenced by the supply and demand for mortgage-backed securities (MBS). According to Investopedia:
“Mortgage-backed securities (MBS) are investment products similar to bonds. Each MBS consists of a bundle of home loans and other real estate debt bought from the banks that issued them . . . The investor who buys a mortgage-backed security is essentially lending money to home buyers.”
Demand for MBS helps determine the spread between the 10-Year Treasury Yield and the 30-year fixed mortgage rate. Historically, the average spread between the two is 1.72 (see chart below):
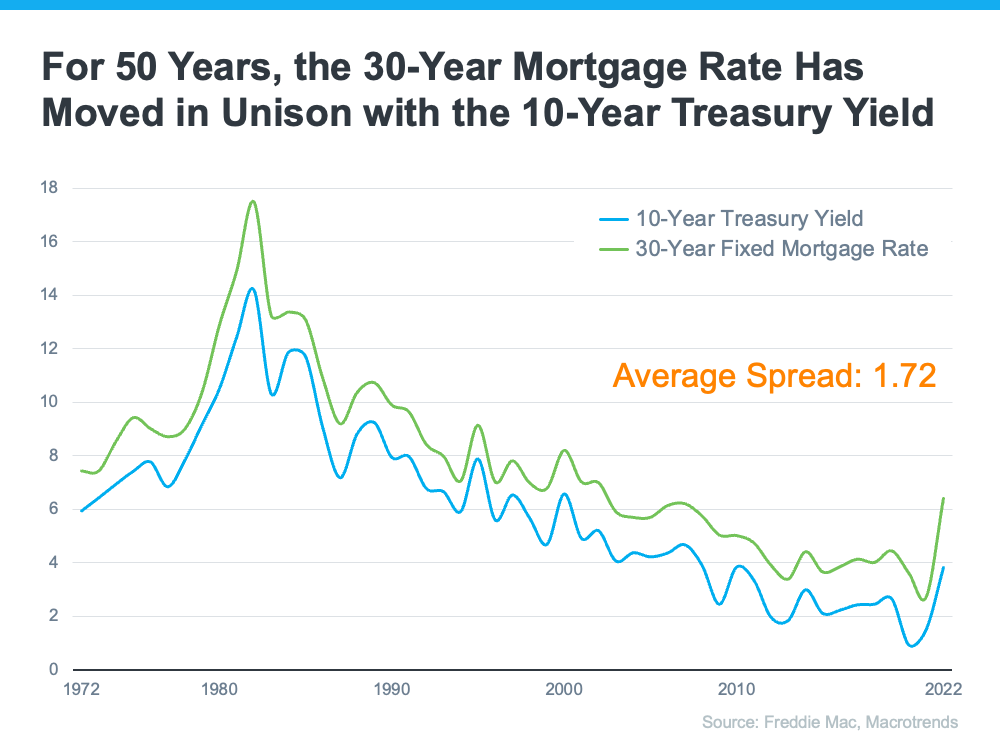
Last Friday morning, the mortgage rate was 6.85%. That means the spread was 3.2%, which is almost 1.5% over the norm. If the spread was at its historical average, mortgage rates would be 5.37% (3.65% 10-Year Treasury Yield + 1.72 spread).
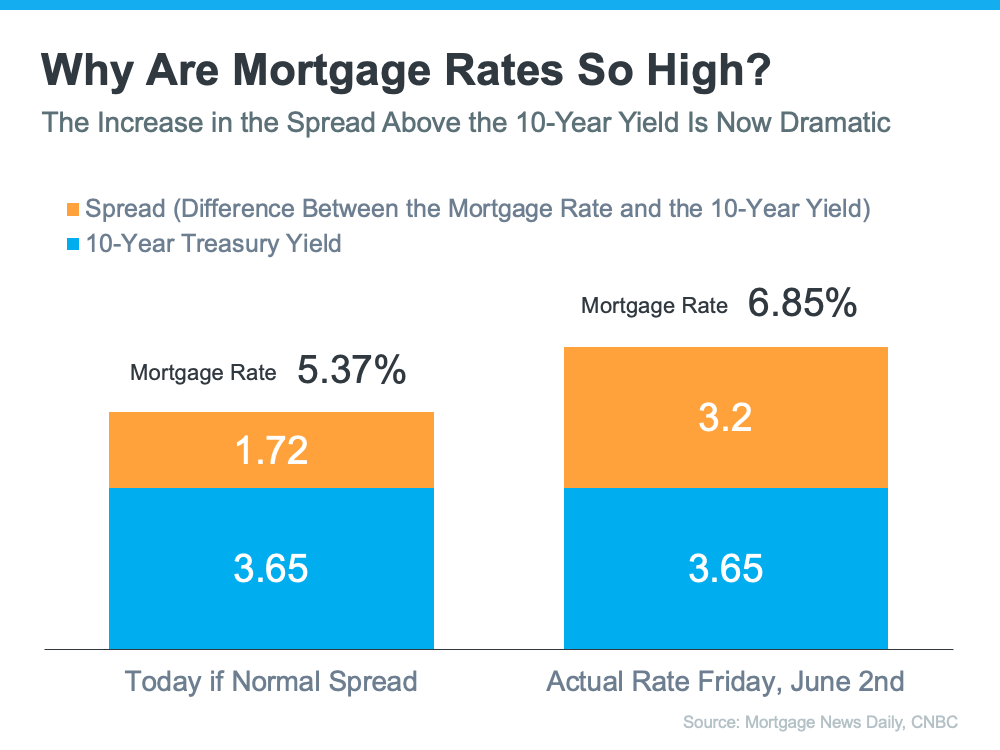
This large spread is very unusual. As George Ratiu, Chief Economist at Keeping Current Matters (KCM), explains:
“The only times the spread approached or exceeded 300 basis points were during periods of high inflation or economic volatility, like those seen in the early 1980s or the Great Financial Crisis of 2008-09."
The graph below uses historical data to help illustrate this point by showing the few times the spread has increased to 300 basis points or more:
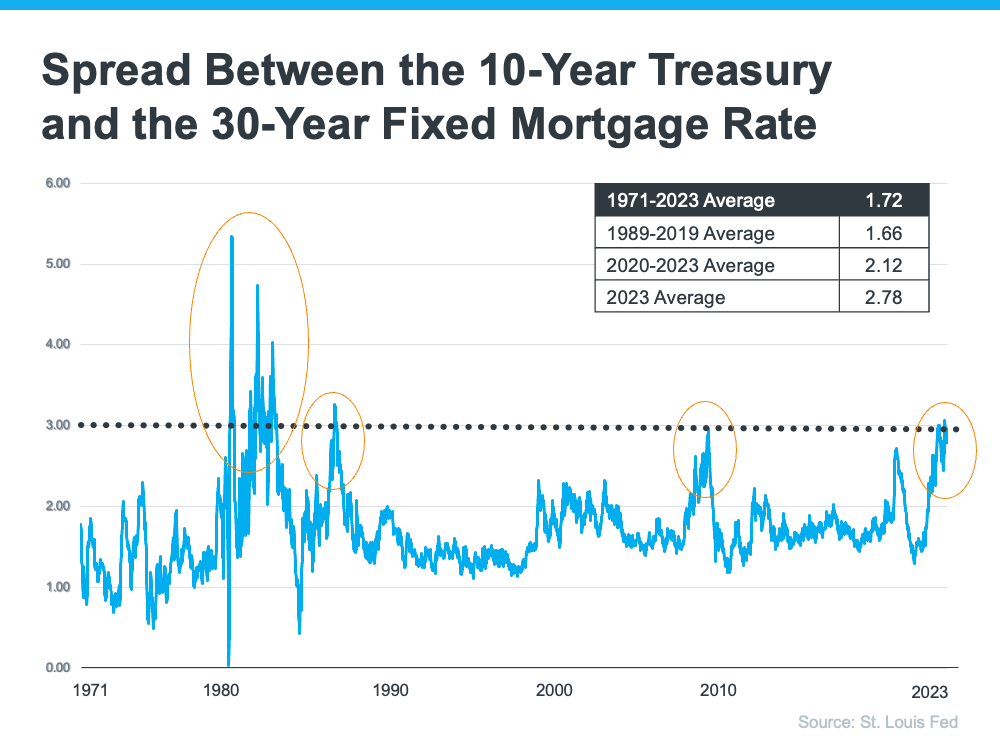
The graph shows how the spread has come down after each peak. The good news is, that means there’s room for mortgage rates to improve today.
So, what’s causing the larger spread and making mortgage rates so high today?
The demand for MBS is heavily influenced by the risks associated with investing in them. Today, that risk is impacted by broader market conditions like inflation and fear of a potential recession, the Fed’s interest rate hikes to try to bring down inflation, headlines that create unnecessarily negative narratives about home prices, and more.
Simply put: when there’s less risk, demand for MBS is high, so mortgage rates will be lower. On the other hand, if there’s more risk with MBS, demand for MBS will be low, and we’ll see higher mortgage rates as a result. Currently, demand for MBS is low, so mortgage rates are high.
Odeta Kushi, Deputy Chief Economist at First American, answers that question in a recent blog:
“It’s reasonable to assume that the spread and, therefore, mortgage rates will retreat in the second half of the year if the Fed takes its foot off the monetary tightening pedal and provides investors with more certainty. However, it’s unlikely that the spread will return to its historical average of 170 basis points, as some risks are here to stay.”
The spread will shrink when the fear investors feel is eased. That’ll mean we should see mortgage rates moderate as the year goes on. However, when it comes to forecasting mortgage rates, no one can know for sure exactly what will happen.
Associate Broker, SRES, CNE, ABR, SFR Bruce has been serving Buyers and Sellers with their real estate needs since 1991. He actively services real estate clients in Wayne, Oakland, and Washtenaw count....
Do You Know How Much Your House Is Really Worth?Want to know something important you probably don’t have a professional check for you nearly as often as you should? Spoiler alert: it’s
Four Ways Your Home Equity Can Work for YouYou may have heard homeowners today have a lot of equity built up. But what does that really mean? Let’s break it down.Because your equity isn&rsquo
Why So Many Homeowners Are Downsizing Right NowFor a growing number of homeowners, retirement isn’t some distant idea anymore. It’s starting to feel very real.According to Realtor.com
How To Stretch Your Options, Not Your BudgetOne of the biggest homebuying advantages you can give yourself today is surprisingly simple: a flexible wish list.Think of it like this. Your wish list
 Listing information is provided by Participants of the MichRIC MLS. IDX information is provided exclusively for personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information deemed reliable but not guaranteed. ©: MichRIC MLS. Last Update September 23, 2026 2:07 PM UTC
 IDX provided courtesy of Realcomp II Ltd., via Preferred, Realtors Ltd and The Originating MLS(found above), © 2026 Realcomp II Ltd. Shareholders. The information being provided is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data is updated as of September 23, 2026 12:49 PM UTC Information deemed reliable but not guaranteed.
The data relating to real estate
on this web site comes in part from the Internet Data Exchange (IDX) Program of Realcomp Ltd. Real estate listings held by firms other than Preferred, Realtors Ltd are marked with the Realcomp Internet Data Exchange logo or thumbnail logo and detailed information about them includes the Listing Broker's Firm Name.
The information being provided is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Show More...
